

 Back
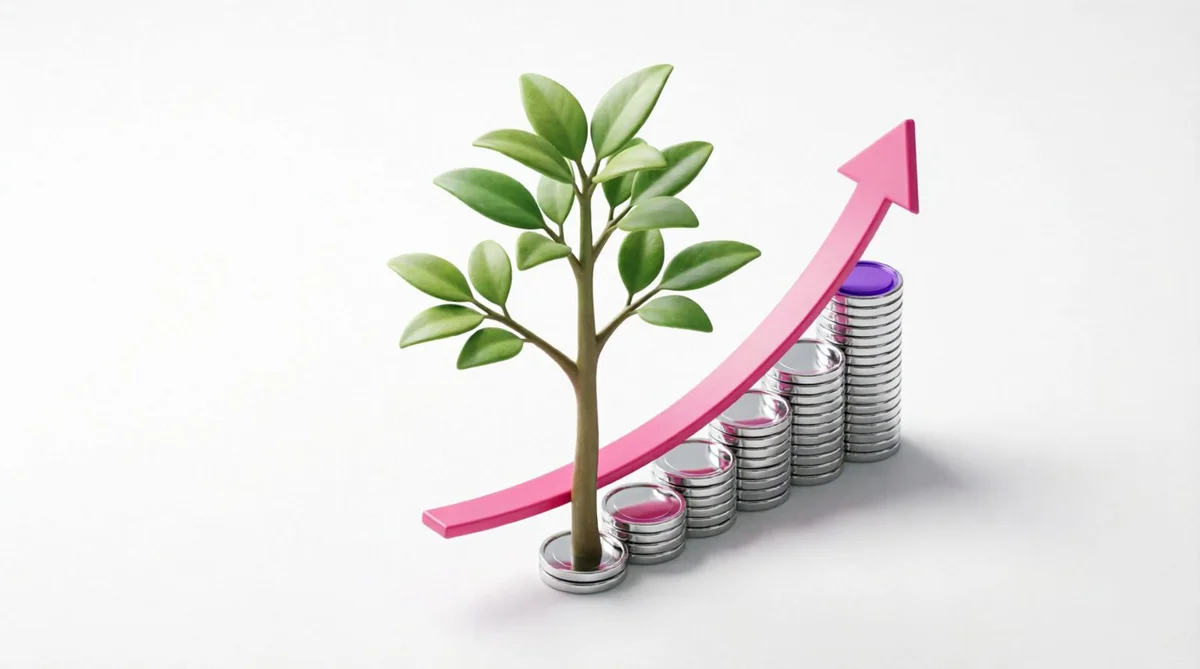
What is compound interest and how does it work
Why Time is More Important than the Amount and How Reinvestment Works
Compound interest is often referred to as the main force in investments. It sounds complicated, but in reality, the idea is simple: not only does your initial deposit earn income, but the already earned amount does as well. Let's break it down with an example.
Simple and Compound Interest — What's the Difference
With simple interest, income is calculated only from the initial amount. With compound interest, earnings are calculated on the accumulated amount as well. That means what you earn is not withdrawn, but continues to work further, generating its own income.
An Example for Clarity
Let's say you invested $1,000 at a nominal 10% per year. After one year, it's $1,100. In the second year, the 10% is calculated from $1,100 — resulting in $1,210, not $1,200. The difference may seem trivial at first, but over the years, it grows like a snowball. This is an illustrative calculation with rounded numbers and not a promise of specific returns.
Why Time Matters More Than the Amount
Compound interest reveals its magic over a long period. The longer money works, the more noticeable the effect — hence one who started earlier with a small amount often overtakes one who invested more but later. The main resource here is not the size of the capital, but the time.
How It Works in Investments
In stocks, compound interest kicks in through reinvestment: the dividends you receive are not spent but used to purchase new securities. In turn, these also start generating dividends. Thus, capital builds itself up.
How to Start
To activate this mechanism, you need access to the stock exchange and regularity. You can open an account and purchase dividend stocks and ETFs online, using the "Stock Broker" app — a broker licensed by the Ministry of Finance of Tajikistan with access to the US market. Most importantly, start: even small but regular investments work for you over time.
This material is for informational purposes only and is not individual investment advice. Investment returns are not guaranteed, past performance does not determine future results.

Calls within Tajikistan are free
Investments
Information


The information provided is for informational purposes only and should not be considered as an offer to buy or sell foreign currency, securities and/or other financial instruments. The information presented on this website is not an individual investment recommendation. Financial instruments or transactions mentioned in this section may not be suitable for you, may not correspond to your investment profile, financial situation, investment experience, knowledge, investment objectives, attitude to risk and profitability.
LLC "Exchange Broker" does not guarantee and does not promise future profitability of investments, does not guarantee the reliability of possible investments and the stability of possible income. Investment results in the past do not guarantee income in the future.
LLC "Exchange Broker" is not responsible for possible investor losses in the event of transactions and investments in financial instruments, and also does not guarantee the return, effectiveness and profitability of investments.
LLC "Exchange Broker" hereby informs that it operates in the securities market in accordance with the following professional participant licenses issued by the Ministry of Finance of the Republic of Tajikistan: depository activity No.010/25 dated 25.06.2025; brokerage activity No.007/25 dated 25.06.2025; dealer activity No.008/25 dated 25.06.2025 and securities management activity No.009/25 dated 25.06.2025, and also informs about the risk of a conflict of interest, including as a result of combining various types of professional activity in the securities market.