


 Back
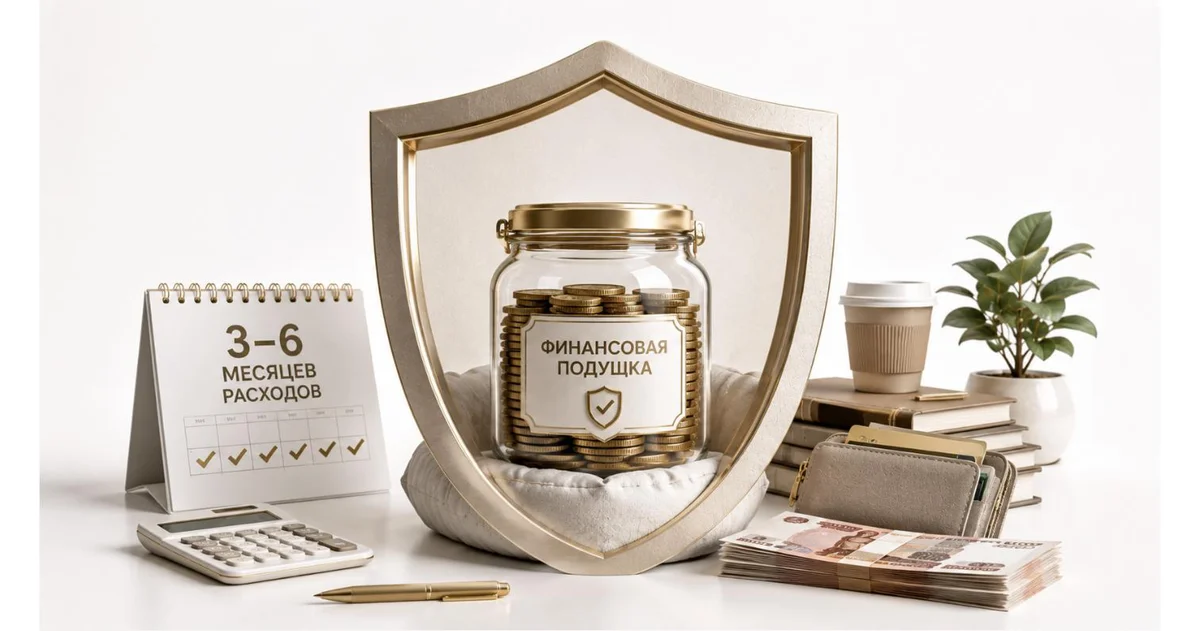
Financial Safety Cushion: How Much You Need and How to Save Up
A financial safety cushion is money set aside not for capital growth, but in case of an unexpected loss of income: job loss, illness, urgent move.
How much to set aside
The generally accepted guideline is 3–6 months' worth of living expenses, not income. If your mandatory expenses (housing, food, family remittances, transportation) are, say, $500 a month, a cushion of $1,500–$3,000 covers most typical income interruptions. For those whose income is less stable — for example, seasonal work — it is wiser to aim for the upper end of the range.
Why this is not the same as investments
A safety cushion and an investment portfolio serve different purposes. The cushion should be readily available and without any loss in value — therefore, it should not be kept in volatile assets that might be in the red at a critical moment. It's wise to invest money left beyond the cushion and not needed in the near future.
How to save if your income is unstable or goes to remittances
You can start with a small fixed amount every month — regularity is more important than the size of the contribution. It’s useful to keep the cushion separate from the main account to avoid spending it impulsively, and gradually replenish it even if the amount seems small: over a year, small contributions add up to a noticeable reserve.
This material is for informational purposes only and is not an individual investment recommendation.

Calls within Tajikistan are free
Investments
Information


The information provided is for informational purposes only and should not be considered as an offer to buy or sell foreign currency, securities and/or other financial instruments. The information presented on this website is not an individual investment recommendation. Financial instruments or transactions mentioned in this section may not be suitable for you, may not correspond to your investment profile, financial situation, investment experience, knowledge, investment objectives, attitude to risk and profitability.
LLC "Exchange Broker" does not guarantee and does not promise future profitability of investments, does not guarantee the reliability of possible investments and the stability of possible income. Investment results in the past do not guarantee income in the future.
LLC "Exchange Broker" is not responsible for possible investor losses in the event of transactions and investments in financial instruments, and also does not guarantee the return, effectiveness and profitability of investments.
LLC "Exchange Broker" hereby informs that it operates in the securities market in accordance with the following professional participant licenses issued by the Ministry of Finance of the Republic of Tajikistan: depository activity No.010/25 dated 25.06.2025; brokerage activity No.007/25 dated 25.06.2025; dealer activity No.008/25 dated 25.06.2025 and securities management activity No.009/25 dated 25.06.2025, and also informs about the risk of a conflict of interest, including as a result of combining various types of professional activity in the securities market.